Rising NPAs Are a Wake-Up Call for NBFCs
India’s NBFC sector is under pressure. The alarming rise in Non-Performing Assets (NPAs) is sending a clear signal—NBFCs need to act now.
From unsecured personal loans to SME and rural lending, defaults are surging across portfolios. What was once considered manageable risk is now becoming a major threat to the financial health of many NBFCs.
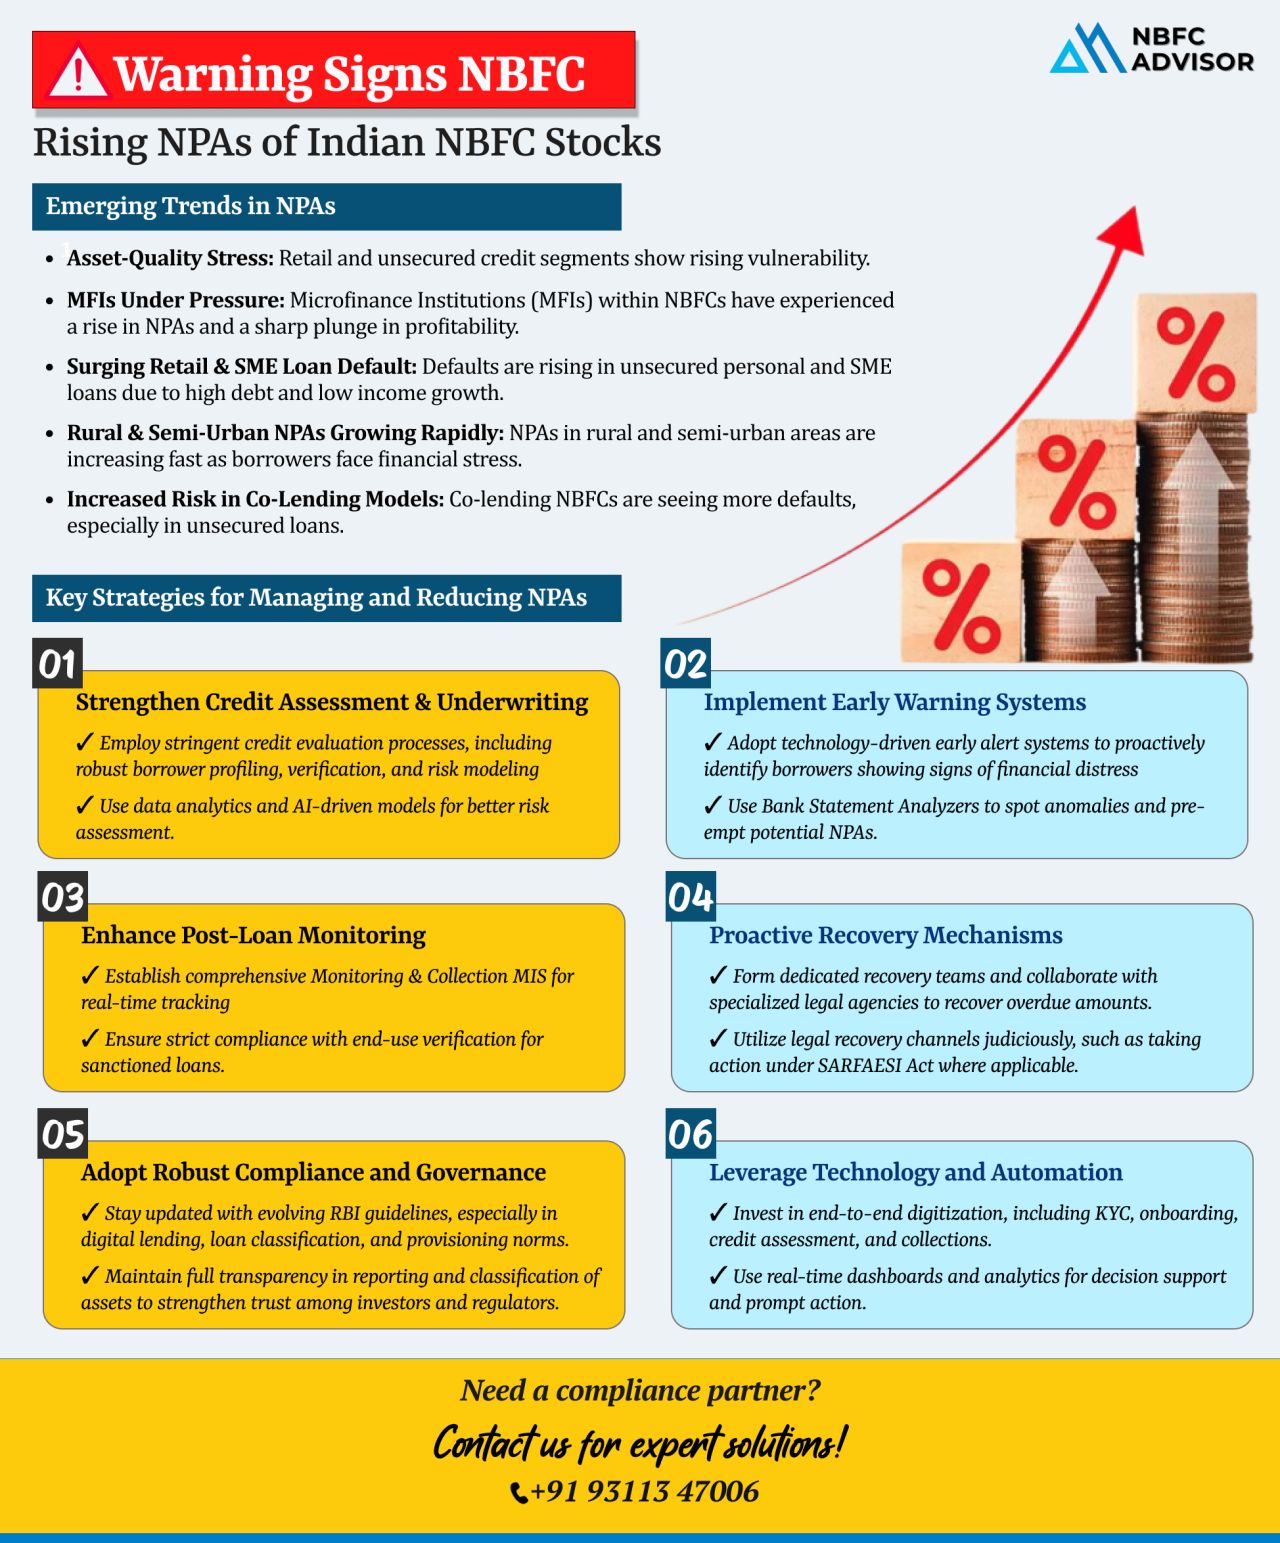
🚨 What’s Driving the NPA Spike?
Several key factors are contributing to the sharp increase in NPAs across the NBFC landscape:
→ Retail and SME Credit Defaults
Both individual borrowers and small businesses are struggling with repayments due to inflationary pressure, reduced income, and inconsistent cash flows.
→ Aggressive Digital Lending Without Due Diligence
In the rush to scale, many NBFCs—especially digital-first lenders—have loosened their underwriting standards, leading to high exposure to weak borrowers.
→ Stress in Co-Lending Models with Fintechs
While co-lending partnerships offer scale, poor alignment in risk management, customer verification, and recovery often leads to greater default rates.
✅ How NBFCs Can Take Back Control
To curb rising NPAs and strengthen your portfolio, here’s what your NBFC should focus on:
1. Strengthen Credit Assessment & Borrower Profiling
Move beyond basic KYC. Implement in-depth financial analysis, behavioral scoring, and alternative credit data for more accurate borrower profiling.
2. Use AI-Powered Early Warning Systems
Technology can help flag at-risk borrowers before they default. AI and predictive analytics can identify red flags based on spending patterns, repayment delays, and more.
3. Enhance Post-Disbursement Monitoring
Loan monitoring shouldn’t stop at disbursal. Regular follow-ups, customer engagement, and usage tracking can help mitigate defaults early.
4. Improve Recovery Mechanisms
A tech-driven, customer-friendly yet firm recovery process is essential. Combine automation with a human approach to boost recovery rates without damaging relationships.
5. Ensure End-to-End Digital Compliance
Digitize documentation, verification, and approval flows to reduce manual errors and regulatory gaps. Transparency and audit readiness start with a strong digital backbone.
6. Stay Updated with RBI Norms
RBI’s evolving guidelines on provisioning, reporting, and restructuring must be followed diligently. Non-compliance can not only increase financial risk but also invite regulatory penalties.
📉 Managing NPAs Means Securing Your NBFC’s Future
Addressing NPAs isn't just about recovering loans—it's about building a resilient, scalable NBFC model. With the right mix of technology, compliance, and governance, your organization can weather the storm and emerge stronger.
📞 Need Expert Help?
If your NBFC is facing rising NPAs or struggling with compliance and internal audits, we can help.
👉 Get in touch for a free consultation.
📞 +91 93113 47006
#NBFCAdvisor #NPAs #NBFCCompliance #RiskManagement #Fintech #DigitalLending #CompliancePartner #AuditReady #Governance